Backtesting Strategies with PredictIndicators.ai: The Complete Guide to Validation and Optimization
Backtesting is the bridge between theory and reality in trading. It's where you find out if your strategy actually works or if it's just a nice idea that falls apart in real markets. But here's the uncomfortable truth: most traders backtest incorrectly. They cherry-pick data, ignore transaction costs, overfit their parameters, and end up with strategies that look great on paper but fail miserably in live trading.
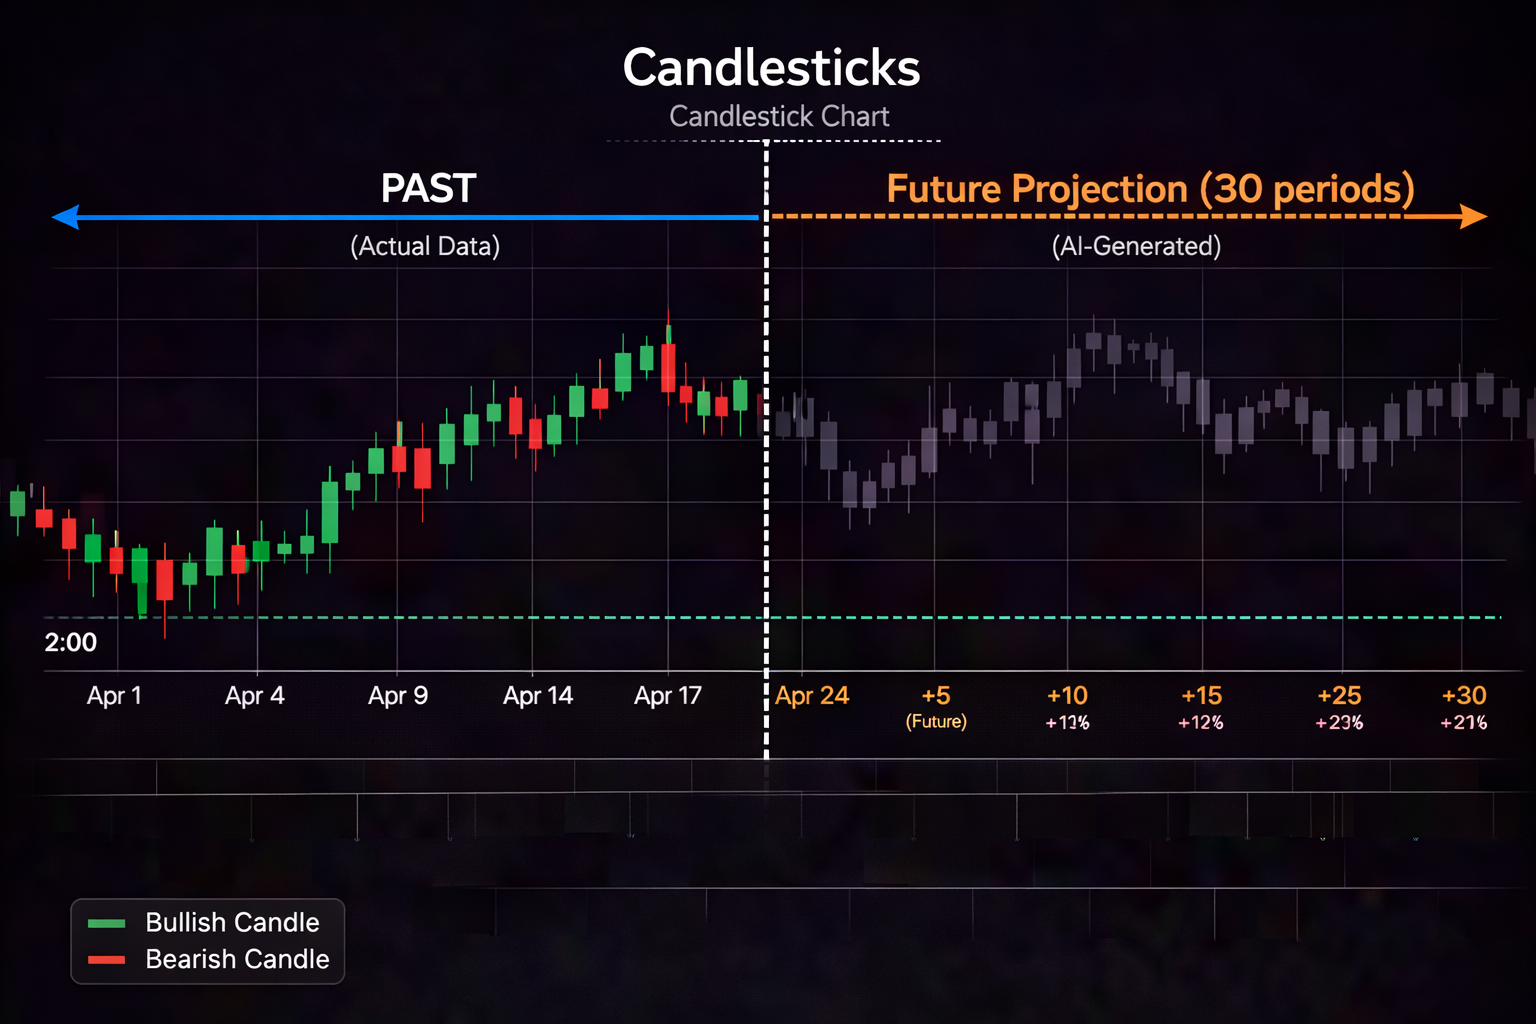
When you add AI-powered forecasting tools like PredictIndicators.ai into the mix, backtesting becomes both more powerful and more complex. AI can dramatically improve your strategy's edge, but only if you validate it properly. This comprehensive guide walks you through everything you need to know about backtesting AI-enhanced trading strategies—from setting up your testing framework to avoiding common pitfalls that destroy accounts.
Why Backtesting AI Strategies is Different
Traditional backtesting involves testing rules like "buy when RSI crosses above 30." AI-enhanced backtesting adds a critical layer: you're testing not just the entry rules, but the accuracy of the AI's predictions themselves.
What Makes AI Backtesting Unique
Two-Layer Validation: You're testing both your trading rules AND the AI's forecast accuracy
Time-Dependent Signals: AI forecasts have prediction horizons (e.g., "bullish for next 30 bars"), requiring time-based evaluation
Dynamic Adaptation: AI models may perform differently across various market conditions (trending vs. ranging, high vs. low volatility)
Confidence Metrics: Many AI tools provide confidence scores that can be incorporated into position sizing and trade filtering
The good news? Platforms like PredictIndicators.ai work seamlessly across NinjaTrader 8, MetaTrader 5, and even mobile platforms (iPhone, iPad, Android), making it easy to backtest once and deploy across multiple trading environments. The same AI forecasts that power your backtests also drive your live trading, ensuring consistency between testing and execution.
Setting Up Your Backtesting Framework
Before running a single backtest, you need a solid framework. Here's how to set it up properly:
Step 1: Choose Your Backtesting Platform
Your choice depends on what markets you trade and where your AI tool integrates:
Best for: Futures traders, NinjaTrader users, advanced technical analysis
AI Integration: PredictIndicators.ai integrates directly as custom indicators
MetaTrader 5 (Forex, CFDs, Multi-Asset)
Pros: Multi-currency testing, genetic optimization, large user community
Best for: Forex traders, automated EA development, multi-asset portfolios
AI Integration: AI tools available as custom indicators or EA components
Python-Based Backtesting (Custom Solutions)
Pros: Maximum flexibility, can integrate any AI model, full control over logic
Best for: Programmers, quantitative traders, custom AI models
Libraries: Backtrader, Zipline, PyAlgoTrade
Step 2: Define Your Testing Universe
What will you test on? Be specific:
Instruments: Which symbols? (ES, NQ, EURUSD, BTCUSD, etc.)
Timeframes: What chart timeframes? (1-min, 5-min, 15-min, 1-hour, etc.)
Date Range: How much historical data? (Minimum 6 months, ideally 2+ years)
Market Conditions: Ensure your range includes trending, ranging, high volatility, and low volatility periods
Warning: Testing only on recent bull market data will give misleading results. Your backtest should include the 2020 crash, 2022 bear market, and various market regimes to ensure robustness.
Step 3: Document Your Strategy Rules
Before backtesting, write down every rule with absolute precision. Ambiguity kills backtest validity:
Entry Rules
Exact conditions that trigger entry (e.g., "AI forecasts MACD bullish AND Stochastics bullish for next 25+ bars")
Time-of-day restrictions (e.g., "Only trade between 9:30 AM - 4:00 PM EST")
Maximum number of trades per day
Minimum time between trades
Exit Rules
Stop loss placement method (fixed points, ATR-based, support/resistance)
Take profit method (fixed target, trailing stop, AI forecast reversal)
Time-based exits (e.g., "Exit all positions by 3:55 PM")
Backtesting with PredictIndicators.ai: A Practical Walkthrough
Let's walk through a real backtesting example using PredictIndicators.ai-style AI forecasts. This example uses NinjaTrader 8, but the principles apply to any platform.
Strategy Definition
We'll backtest a simple AI-enhanced momentum strategy:
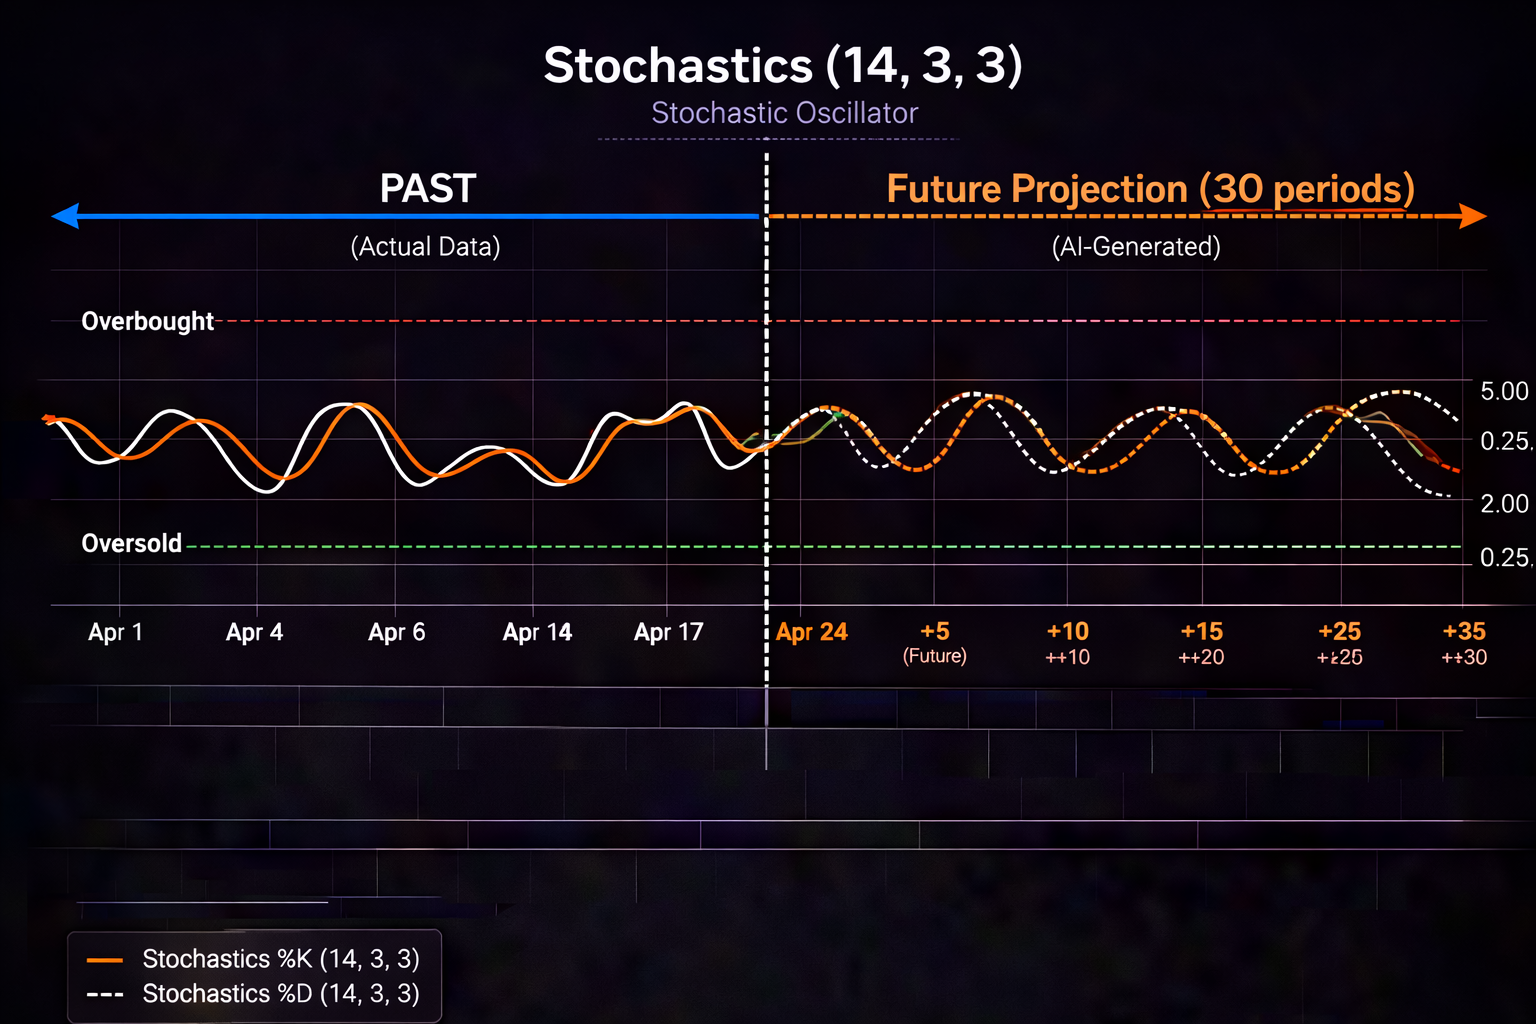
Entry Long: AI forecasts show MACD bullish AND Stochastics bullish AND ATR stable for next 25-30 bars
Entry Short: AI forecasts show MACD bearish AND Stochastics bearish AND ATR stable for next 25-30 bars
Stop Loss: 2x ATR from entry price
Take Profit: 4x ATR from entry price (2:1 reward-to-risk)
Position Size: 1% risk per trade
Trading Hours: 9:30 AM - 4:00 PM EST (regular futures session)
Max Trades: 5 per day
Instrument: E-mini S&P 500 (ES)
Timeframe: 5-minute charts
Backtest Period: January 2024 - December 2025 (2 years)
Step 1: Set Up the Strategy in NinjaTrader 8
Open NinjaTrader 8 Strategy Builder
Create new strategy: "AI_Momentum_Strategy"
Add PredictIndicators.ai as an indicator to the strategy
Define input parameters for AI forecast bars (25, 30, 35), stop loss multiplier (2.0), take profit multiplier (4.0)
Code entry logic to check AI forecast buffers for bullish/bearish alignment
Code exit logic for stop loss and take profit based on ATR
Add filters for trading hours and maximum daily trades
Step 2: Configure Strategy Tester
Open Strategy Tester (Tools → Strategy Analyzer)
Select "AI_Momentum_Strategy" from dropdown
Instrument: ES 03-26 (front month E-mini S&P)
Timeframe: 5 minute
Date Range: 01/01/2024 - 12/31/2025
Testing Mode: "Every tick" (most accurate)
Starting Balance: $50,000
Commission: $4.50 per round turn (realistic for futures)
Slippage: 1 tick ($12.50 for ES)
Step 3: Run Initial Backtest
Click "Run" and wait for the backtest to complete. This may take several minutes depending on data volume.
Once complete, you'll see a report with key metrics like:
Net Profit
Total Trades
Win Rate
Profit Factor
Max Drawdown
Average Trade
Sharpe Ratio
Step 4: Analyze the Results
Sample Backtest Results (Hypothetical)
Net Profit: $34,567
Total Trades: 487
Win Rate: 64.3%
Profit Factor: 2.14
Max Drawdown: $4,234 (8.5% of starting balance)
Average Win: $187
Average Loss: -$94
Largest Win: $1,245
Largest Loss: -$312
Average Trade Duration: 47 minutes
Sharpe Ratio: 1.87
Key Metrics to Evaluate
Don't just look at net profit. These metrics tell you whether your strategy is actually viable:
1. Profit Factor
Formula: Gross Profit / Gross Loss
Target: 1.5 or higher
Profit factor measures how much you make per dollar lost. A profit factor of 2.0 means you make $2 for every $1 lost. Below 1.2, the strategy probably isn't worth trading. Above 2.5, you may be overfit.
2. Win Rate vs. Reward-to-Risk
These two metrics work together:
High win rate (65%+) with low reward-to-risk (1:1) can be profitable
Low win rate (40%) with high reward-to-risk (3:1) can also be profitable
Your combination determines expectancy
Expectancy Formula: (Win Rate × Average Win) - (Loss Rate × Average Loss)
Positive expectancy is non-negotiable. If expectancy is negative, no amount of optimization will save the strategy.
3. Maximum Drawdown
Definition: Largest peak-to-trough decline in account value
Target: Less than 15-20% of starting balance
Drawdown tells you the worst-case scenario you faced during the backtest. If max drawdown is 30%, can you emotionally handle that in live trading? Be honest.
4. Recovery Factor
Formula: Net Profit / Max Drawdown
Target: 3.0 or higher
Recovery factor measures how efficiently your strategy recovers from losses. A recovery factor of 5.0 means you made 5x your maximum drawdown in profit.
5. Sharpe Ratio
Definition: Risk-adjusted return metric
Target: 1.0 or higher (above 2.0 is excellent)
Sharpe ratio accounts for volatility in returns. A strategy with steady gains has a higher Sharpe ratio than one with wild swings, even if both have the same net profit.
6. Average Trade Duration
This affects your capacity and opportunity cost:
Short duration (under 30 minutes): Scalping, high frequency, requires fast execution
Medium duration (30 minutes - 4 hours): Day trading, manageable
Long duration (4+ hours): Swing trading, overnight risk
Optimization: Finding the Sweet Spot
Once your initial backtest shows promise, optimization helps you fine-tune parameters. But optimization is dangerous—done poorly, it leads to overfitting and strategies that fail in live markets.
The Optimization Process
Identify Parameters to Optimize: Choose 3-5 key parameters (e.g., AI forecast bars, stop loss multiplier, take profit multiplier, ATR period)
Set Reasonable Ranges: Don't optimize over huge ranges. For forecast bars, test 20, 25, 30, 35, 40—not 5 to 100.
Use Genetic Optimization First: NinjaTrader 8 and MT5 both offer genetic algorithm optimization that quickly identifies promising parameter regions.
Review Top Results: Look for parameter sets that appear repeatedly in top-performing combinations.
Validate with Walk-Forward Analysis: Test optimized parameters on data NOT used in optimization.
Walk-Forward Analysis: The Gold Standard
Walk-forward analysis prevents overfitting by testing on out-of-sample data:
Process:
In-Sample Period: Optimize on data from Jan 2024 - Jun 2024 (6 months)
Out-of-Sample Period: Test optimized parameters on Jul 2024 - Sep 2024 (3 months)
Repeat: Optimize on Apr 2024 - Sep 2024, test on Oct 2024 - Dec 2024
Continue: Roll forward through your entire dataset
Evaluate: If out-of-sample results are close to in-sample results (within 20-30%), your strategy is robust. If out-of-sample performance collapses, you're overfit.
Red Flag: If your optimized strategy has a profit factor of 3.5 in-sample but only 1.2 out-of-sample, you've curve-fit. Return to the drawing board.
Parameter Stability Test
Good parameters work across a range, not just at one specific value:
Example: Testing AI Forecast Bars parameter
20 bars: Profit factor 1.8
25 bars: Profit factor 2.1
30 bars: Profit factor 2.2 ← Optimal
35 bars: Profit factor 2.1
40 bars: Profit factor 1.9
This is a stable parameter—performance remains strong across a range centered on 30 bars.
Contrast with unstable parameter:
20 bars: Profit factor 1.3
25 bars: Profit factor 1.4
27 bars: Profit factor 3.2 ← Only works at this exact value
30 bars: Profit factor 1.2
35 bars: Profit factor 1.1
This is overfit. The strategy only works at exactly 27 bars—a statistical fluke, not a genuine edge.
Avoiding Common Backtesting Mistakes
Even experienced traders make these errors. Don't let them sabotage your work:
Mistake 1: Look-Ahead Bias
Problem: Using information in your backtest that wouldn't be available in real-time.
Example: Calculating stops based on the day's high/low (which you don't know until the day ends).
Solution: Only use data available at the time of each trade. Most professional backtesting platforms prevent this automatically, but be careful with custom calculations.
Mistake 2: Survivorship Bias
Problem: Testing only on instruments that exist today, ignoring those that went bankrupt or were delisted.
Example: Backtesting a stock strategy only on current S&P 500 components, ignoring companies that were removed.
Solution: Use databases that include delisted symbols, or focus on futures/forex where this isn't an issue.
Mistake 3: Ignoring Transaction Costs
Problem: Not accounting for commissions, spreads, and slippage.
Example: A scalping strategy shows $50,000 profit in backtest, but after $4.50 commissions per trade and 1-tick slippage on 500 trades, profit drops to $25,000.
Solution: Always include realistic transaction costs:
Futures: $4-5 per round turn + 1 tick slippage
Forex: Spread (1-3 pips major pairs) + potential slippage
Stocks: Commission per share + bid-ask spread
Mistake 4: Overfitting
Problem: Optimizing so specifically to historical data that the strategy fails on new data.
Signs of Overfitting:
Too many optimization parameters (more than 5-6)
Parameters only work at exact values, not in ranges
Out-of-sample performance much worse than in-sample
Equity curve is too smooth (real trading has drawdowns)
Solution: Keep strategies simple, use walk-forward analysis, test on out-of-sample data, and accept that real performance will be 20-30% worse than backtests.
Mistake 5: Insufficient Sample Size
Problem: Drawing conclusions from too few trades.
Example: A strategy with 23 trades and high looks amazing, but it's statistically meaningless.
Solution: Minimum 100 trades for preliminary validation, 300+ trades for confidence, 500+ for high confidence.
Mistake 6: Data Quality Issues
Problem: Using poor-quality or incomplete historical data.
Signs:
Gaps in data (missing bars)
Incorrect volume data
Unrealistic price spikes
Missing overnight sessions (for futures)
Solution: Use data from reputable providers (CQG, Rithmic, IQFeed for futures; quality broker data for forex). Verify data integrity before backtesting.
Advanced Backtesting Techniques
Multi-Market Testing
Test your strategy across multiple instruments to ensure it's not specific to one market:
Example: Test your AI momentum strategy on:
ES (E-mini S&P 500)
NQ (E-mini Nasdaq)
CL (Crude Oil)
GC (Gold)
EURUSD (Forex)
If the strategy works across uncorrelated markets, it's more likely to be robust and generalizable.
Monte Carlo Simulation
Monte Carlo analysis tests how your strategy performs under random variations:
Process:
Randomize trade sequence (shuffle the order of trades from your backtest)
Randomize slippage (vary slippage from 0-2 ticks randomly)
This reveals your strategy's robustness to real-world variability. If 90% of Monte Carlo simulations are profitable, you can have confidence. If only 55% are profitable, the strategy is fragile.
Regime Analysis
Test how your strategy performs in different market conditions:
Segment your backtest results by market regime:
Strong Uptrend: How did strategy perform?
Strong Downtrend: Profitable or destructive?
Range-Bound: Does strategy whipsaw in consolidation?
High Volatility: Did stops get hit by noise?
Low Volatility: Did strategy fail to generate signals?
Understanding regime-dependent performance helps you know when to trade your strategy and when to sit aside.
From Backtest to Live Trading: The Transition
Backtesting is complete. Results look solid. Now what? Don't jump straight into live trading—follow a phased approach:
Phase 1: Paper Trading (4-8 Weeks)
Trade your strategy in real-time with simulated money
Use the same platform and AI tool you'll use live (NinjaTrader 8, MT5, etc.)
Execute every signal exactly as you would with real capital
Track slippage, fills, and psychological factors
Compare paper trading results to backtest—should be within 20-30%
Red Flag: If paper trading results are significantly worse than backtests, investigate why before going live.
Phase 2: Micro-Live Trading (4-8 Weeks)
Trade with 25-50% of your intended position size
Real money introduces psychological pressure—start small
Monitor execution quality, slippage, and emotional responses
Continue comparing results to backtest expectations
If results align with backtests, gradually increase size
Phase 3: Full Deployment
Scale to full position size over 2-4 weeks
Monitor performance weekly for the first 3 months
Keep detailed trade journal comparing live results to backtest
Be prepared to halt trading if live results deviate significantly (>40% worse than backtest)
Continuous Improvement: Beyond the Initial Backtest
Backtesting isn't a one-time task. Markets evolve, and your strategy should too:
Monthly Reviews
Compare live performance to backtest expectations
Review any losing trades—were they normal variance or signs of degradation?
Check if AI forecast accuracy has changed
Quarterly Re-Backtesting
Add recent 3 months of data to your backtest
Re-run optimization to see if parameters still hold
If recent data shows significant degradation, investigate market regime changes
Annual Strategy Audit
Comprehensive review of entire strategy
Test on new instruments if expanding
Consider adding new features or filters based on learnings
Evaluate whether AI models need recalibration
Building Confidence Through Rigorous Backtesting
The ultimate goal of backtesting isn't just to validate a strategy—it's to build the confidence you need to execute consistently in live markets.
When you know your AI-enhanced strategy has been tested across:
Multiple time periods (bull markets, bear markets, crashes, recoveries)
Realistic transaction costs and slippage
Out-of-sample walk-forward analysis
...you can trade with genuine conviction. When losses come (and they will), you'll know they're normal variance, not a broken strategy. When drawdowns hit, you'll know they're within expected parameters. When wins come, you won't get overconfident—you'll know it's the edge playing out, not luck.
That's the power of rigorous backtesting. It doesn't guarantee profits, but it gives you something invaluable: the confidence to stick with your process through inevitable ups and downs.
Getting Started with PredictIndicators.ai Backtesting
Ready to backtest your AI-enhanced strategies? Here's how to begin:
Set up your platform: Install NinjaTrader 8, MetaTrader 5, or your preferred backtesting environment.
Integrate PredictIndicators.ai: Follow the installation guide to add AI forecasting to your platform. The same tool works across desktop (NinjaTrader, MT5, Mac) and mobile (iPhone, iPad, Android, web), giving you flexibility.
Define your strategy: Write down precise entry, exit, and risk management rules.
Gather quality data: Ensure you have clean, complete historical data for your instruments.
Run initial backtest: Test your strategy without optimization first to see baseline performance.
Optimize carefully: Use genetic optimization and walk-forward analysis to avoid overfitting.
Validate across markets: Test on multiple instruments to ensure robustness.
Paper trade: Transition to live markets through paper trading before risking real capital.
Final Thoughts
Backtesting is where good trading strategies are born—or where bad ideas die quickly. With AI-powered forecasting tools like PredictIndicators.ai, you have a significant edge, but that edge only matters if you validate it properly.
Take the time to backtest rigorously. Avoid shortcuts. Test across multiple markets and conditions. Use walk-forward analysis. Account for transaction costs. Build genuine confidence through data, not hope.
The traders who succeed in 2026 and beyond won't be those with the fanciest AI tools—they'll be the ones who combine cutting-edge technology with old-fashioned discipline in testing and validation. They'll be the ones who know, with data-backed certainty, that their edge is real.
That trader can be you. Start backtesting today.
Trading Disclaimer: This content is for educational and informational purposes only and does not constitute financial advice, investment recommendations, or trading instructions. Backtesting results are not indicative of future performance. All trading involves risk of loss and is not suitable for all investors. Historical performance does not guarantee future results. Always conduct your own research and consult with a licensed financial advisor before making any trading or investment decisions. PredictIndicators.ai is a software tool that provides predictive analytics; it does not guarantee profits or protect against losses. Transaction costs, slippage, and execution quality can significantly impact real-world trading results.